Planning for the future requires more than simply saving money in a bank account. Inflation can gradually reduce the purchasing power of money, while different investment products offer different levels of risk, return and liquidity. Therefore, the best investment for the future is usually not one particular product. It depends on your financial goals, age, income, investment period and ability to handle market fluctuations.
According to SEBI’s investor education material, investors should consider factors such as investment objectives, time horizon, risk appetite and liquidity before choosing an investment. SEBI also recommends diversification rather than depending on a single asset class. investor.sebi.gov.in
What Is the Best Investment for the Future?
For many long-term investors, a diversified combination of equity mutual funds, retirement investments, safe fixed-income products and selected real assets can be more practical than putting all money into one investment.
There is no investment that guarantees high returns without risk. Generally, investments with greater potential returns can also experience greater fluctuations.
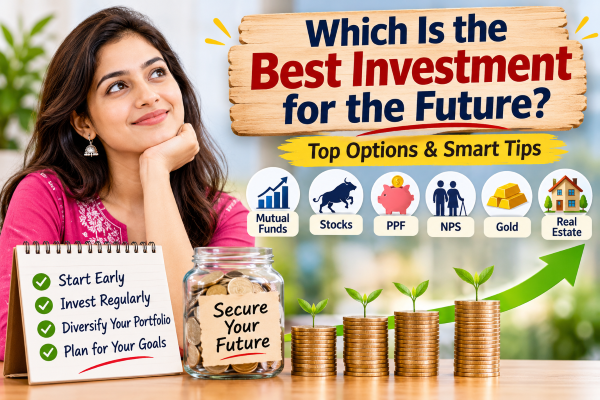
Here are some important options to consider.
1. Mutual Funds Through SIP
Mutual funds can be suitable for investors who want long-term wealth creation but do not want to select individual stocks themselves. A Systematic Investment Plan, or SIP, allows investors to invest a fixed amount regularly.
SEBI notes that mutual funds provide professional fund management and that SIPs allow periodic investment. It also highlights the importance of selecting investments according to risk tolerance and financial goals. investor.sebi.gov.in
Example
Suppose a 30-year-old invests ₹5,000 every month through a diversified equity mutual fund for 20 years.
The total amount invested would be:
₹5,000 × 12 × 20 = ₹12 lakh
If the investment earns an average annual return of 10% over the period, the accumulated value could be around ₹38 lakh.
This is only an illustration. Actual mutual fund returns are market-linked and can be higher or lower.
The biggest advantage of starting early is the power of compounding.
2. Direct Equity or Stocks
Stocks can be another long-term investment option for people who understand businesses and are comfortable with market volatility.
A successful company can increase in value over many years, but individual stocks can also fall substantially. Therefore, investing without research simply because a stock is popular can be risky.
For beginners, diversified investment options may be easier to manage than building a portfolio of individual stocks.
3. Public Provident Fund (PPF)
For investors who prioritize safety and long-term savings, PPF can be an attractive option.
India Post currently lists the PPF interest rate at 7.1% per year, compounded annually. Interest rates for small-savings schemes can change according to government notifications. India Post
Example
Suppose someone invests ₹50,000 per year in PPF for several years.
The investor receives the benefit of long-term compounding while building a relatively stable savings corpus. PPF can therefore be useful for people who want a lower-risk component in their long-term portfolio.
However, investors should understand the account’s rules, contribution limits, withdrawal conditions and tax treatment before investing.
4. National Pension System (NPS)
NPS is designed specifically for long-term retirement planning. It is regulated by the Pension Fund Regulatory and Development Authority (PFRDA).
NPS allows subscribers to choose investment options involving equity, corporate bonds and government securities. The available asset allocation can be selected according to the investor’s preference and risk profile. PFRDA PROD
Example
Consider a 35-year-old employee who contributes ₹5,000 per month to NPS for retirement.
Instead of relying entirely on savings later in life, the person gradually builds a retirement corpus during their working years.
NPS can be particularly relevant for people whose main objective is creating retirement income rather than short-term wealth.
5. Gold
Gold has traditionally been used as a store of value and can provide diversification within a portfolio.
Instead of putting all your savings into physical gold, investors may consider regulated investment routes such as gold-related financial products, depending on their objectives and eligibility.
Gold prices can fluctuate, so it should generally be viewed as one part of a diversified portfolio rather than the only investment.
6. Real Estate
Property can be a long-term investment for people who have substantial capital and understand the local market.
For example, buying a property in an area with improving infrastructure, employment opportunities and population growth may potentially create long-term value.
However, real estate requires significant capital and can involve registration costs, maintenance expenses, taxes and limited liquidity. Selling a property can also take considerably longer than selling many financial investments.
A Simple Future Investment Example
Imagine Rahul, aged 30, who earns ₹60,000 per month.
Instead of putting all his savings into one investment, he could create a diversified strategy based on his goals.
For example:
- ₹5,000 per month — diversified equity mutual fund SIP
- ₹3,000 per month — retirement-oriented investment such as NPS
- ₹2,000 per month — safer savings or fixed-income investment
- Separate emergency fund — maintained in a liquid and accessible form
This is only an illustration, not a recommended allocation for every person.
The idea is to combine investments with different characteristics rather than depending completely on one asset.
How to Choose the Right Investment
Before investing, ask yourself five basic questions:
1. What is my goal?
Retirement, children’s education, home purchase and wealth creation may require different strategies.
2. How long can I stay invested?
Long-term goals can provide more time to handle market fluctuations.
3. How much risk can I tolerate?
Someone who cannot tolerate temporary losses may need a different portfolio from an aggressive long-term investor.
4. Do I need access to the money soon?
Emergency savings should generally not be placed in investments that are difficult to access quickly.
5. Am I diversified?
Diversification can reduce dependence on the performance of a single asset class, although it cannot eliminate investment losses. investor.sebi.gov.in
Final Thoughts
So, which is the best investment for the future? There is no single answer.
For long-term wealth creation, diversified equity mutual funds may be useful for investors who can accept market risk. PPF can provide a relatively stable long-term savings component, while NPS can support retirement planning. Gold and real estate may also have a role depending on the investor’s financial situation and objectives.
The most important principle is to start early, invest consistently, diversify and understand what you are buying. SEBI also advises investors to understand investment products and choose regulated products rather than making decisions based solely on promises of high returns. investor.sebi.gov.in
Disclaimer: This article is for educational purposes only and should not be considered financial advice. Investment returns are not guaranteed, and market-linked investments involve risk. Consider your financial goals, risk profile and investment horizon, and consult a qualified financial professional before making investment decisions.